
Wall Street's 2024 Outlook for Stocks
Stock markets rose last week, with the S&P 500 gaining 0.8% to close at 4,594.63. The index is now up 19.7% year-to-date, 28.4% from its October 12, 2022 closing low of 3,577.03, and down 4.2% from its January 3, 2022 record closing high of 4,796.56.
As the year draws to a close, Wall Street's top strategists are sharing their insights on where they see the stock market heading in 2024. Typically, the average forecast for the group predicts the S&P 500 climbing by about 10%, in line with historical averages.
This year, however, strategists are offering a wide range of views, with targets ranging from 4,200 to 5,500. This implies potential returns between -8.5% and +19.7% from Friday's close.
Key Factors Driving Market Outlook
Economic Growth: Economists have varying views on whether the U.S. economy will enter a recession in 2024. Those expecting continued expansion forecast modest growth, while those anticipating a recession believe it will be brief and mild.
Earnings Growth: Most strategists expect S&P 500 earnings to grow in 2024 despite lackluster GDP growth forecasts. This may be due to expectations of a shift in consumer spending from services to goods and the S&P's greater exposure to the goods sector.
Profit Margins: Many strategists expect profit margins to remain high, supported by improved operating efficiencies. However, rising interest rates could pose a headwind for earnings growth.
Monetary Policy: Strategists agree that the worst of the inflation crisis is behind us. This suggests that the Federal Reserve may have room to loosen financial conditions with interest rate cuts if economic conditions deteriorate significantly.
Valuations: Strategists are divided on whether valuations are reasonable or slightly high. The debate is unlikely to go away soon, as valuations have historically provided little insight into short-term market moves.
Strategists' 2024 S&P 500 Price Targets
Below is a summary of 12 analysts' S&P 500 price targets for 2024, along with highlights from their commentary:
Firm
Target
EPS Estimate
Commentary
JPMorgan
4,200
$225
Sees modest economic growth, eroding excess savings, and tightening credit as headwinds for earnings growth.
Morgan Stanley
4,500
$229
Expects a recovery in earnings growth next year.
UBS
4,600
$228
Anticipates a mild recession in the middle of the year and a credit market sell-off in Q2.
Wells Fargo
4,625
$235
Expects a volatile and ultimately flattish SPX in 2024.
Goldman Sachs
4,700
$237
Sees modest economic growth, 5% earnings growth, and a valuation of 18x.
Societe Generale
4,750
$230
Expects a roller coaster year with a mild recession in the middle of the year.
Barclays
4,800
$233
Expects single-digit returns as easing inflation is offset by modest economic deceleration.
Bank of America
5,000
$235
Sees further gains in 2024 as the market has absorbed significant geopolitical shocks.
RBC
5,000
$232
Remains constructive on the U.S. equity market despite a sluggish economy and election uncertainty.
Deutsche Bank
5,100
$250
Believes valuations are not high and expects earnings growth to continue.
BMO
5,100
$250
Expects a year of positive returns with more sanguine, broadly distributed performance.
Knightsbridge
5,200
-
Sees potential for further gains driven by enthusiasm for AI technology.
Conclusion
While most strategists produce high-quality research, their one-year price targets should not be taken as definitive
NIST Graded Our Post-Quantum Cryptography. Zero Failures.
NIST's Algorithm Validation Test System generated test vectors nobody had seen, we answered them over the ACVP protocol, and NIST graded the result: 2,130 cases across ML-KEM, ML-DSA and SLH-DSA in every parameter set offered, zero failures, demo certificate A11025. This is what that proves, where we deliberately drew the claim narrower than NIST's own matrix, and why the FIPS 140-2 sunset on 21 September makes the distinction between being graded and grading yourself worth understanding.
The Problem Is Not the Problem
People treat the Jack Sparrow line as a joke. The attribution is a joke. The sentence is not. Forty years in markets says the same thing Epictetus said in 125 CE and Robert Merton named in 1948: the event is finite, and the story you appoint to govern it is not. This essay walks the quote back to its actual sources, draws the loop that turns a feeling into an order, and sets out the four places a rule written in advance cuts the loop. Faith is not a hedge. It is a stance.
What KXCO Is, and Why the Hard Problem Was Never Intelligence
The prevailing enthusiasm assumes the hard problem is intelligence. It is not. It is that banks, hospitals, courts and governments are being asked to let software act on their behalf with no way to establish who decided, on what basis, or whether the record will still read in a decade. KXCO founder Shayne Heffernan sets out the architecture that answers those questions, drawn as a graph, and argues that properly constructed AI is an amplifier of human judgement rather than a replacement for it.
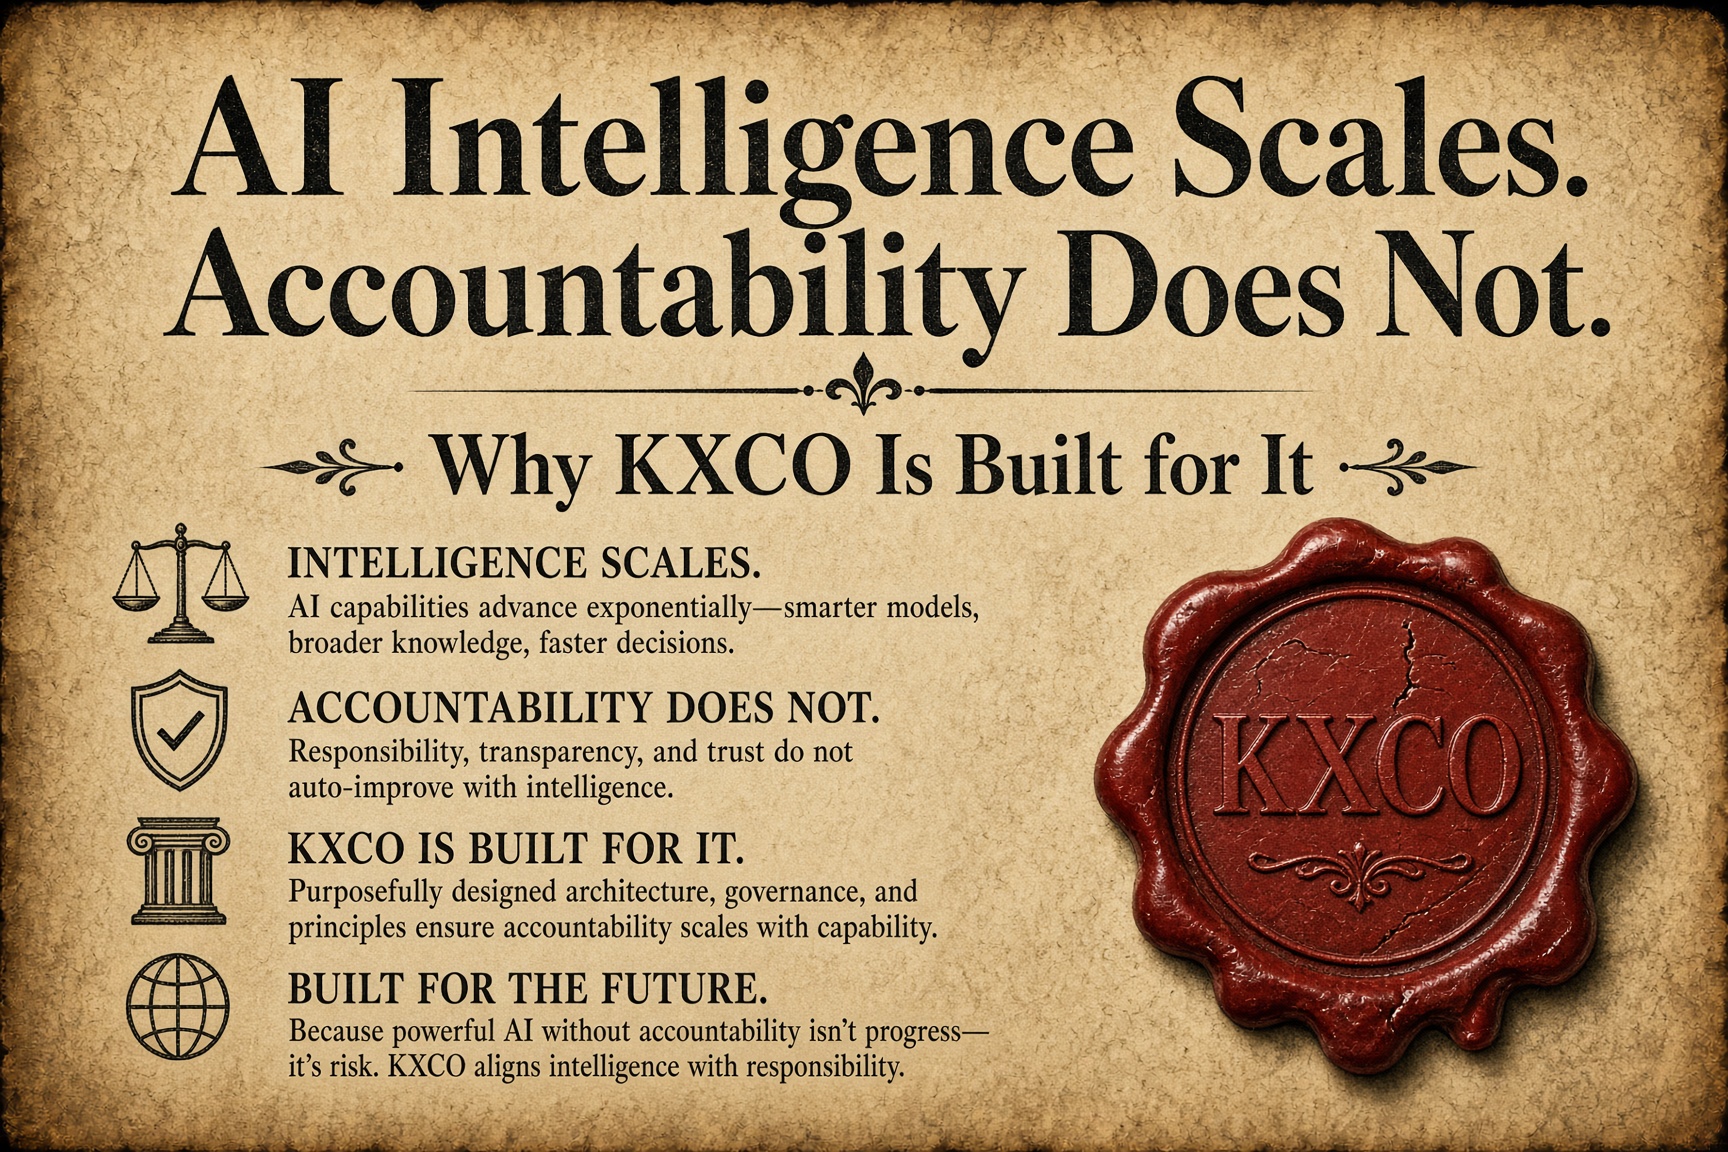
AI Intelligence Scales. Accountability Does Not. Why KXCO Is Built for It.
Capability is becoming abundant and everything abundant gets cheap. What does not get cheap is the person who has to sign, and they can only carry what they can see. Four conditions follow from that, and four independent authorities reached the first of them last month without knowing it.
Every story, signed and delivered.
Subscribe to the kxco channel and get the headline, the AI-written key takeaways, and the chain-anchor link the moment we publish. Audio versions and per-ticker subscriptions arrive in the next iteration.