
Wall Street Week Ahead: Nvidia and Inflation
Wall Street Nvidia's Earnings High and Inflation Data Awaited
Last week, Wall Street witnessed record highs fueled by Nvidia's stellar earnings report, with the S&P 500 and Dow Jones reaching new peaks. However, the upcoming release of inflation data is poised to test this rally. Here's a look at what's in store for investors on Wall Street this week.
Record Highs and Earnings Spotlight: Nvidia's blowout earnings report propelled stocks to record highs, with the S&P 500 and Dow Jones ending the week up approximately 1%. The Nasdaq Composite also saw gains, adding about 0.6%. Notably, both the S&P and Dow closed Friday at all-time highs, reflecting the market's optimism.

Inflation Data Looms: The largest challenge facing markets in the week ahead is the release of the latest Personal Consumption Expenditures (PCE) index, the Federal Reserve's preferred inflation gauge, on Thursday. This data will provide insights into inflation trends, which have been a focal point for investors amid concerns about rising prices.
Inflation Concerns and Market Sentiment: Economists expect the annual "core" PCE, excluding food and energy, to have reached 2.4% in January, signaling potential inflationary pressures. A monthly increase of 0.4% would underscore growing fears that inflation may be more persistent than initially anticipated. However, market sentiment remains cautiously optimistic, with the current sentiment indicator suggesting that markets have not yet entered a euphoric phase.
Retail Sector Earnings: As fourth-quarter earnings season winds down, attention will turn to the retail sector, with companies like Macy's, Best Buy, and TJX set to report. These earnings reports will offer insights into consumer spending trends and the health of the retail industry amid inflation concerns.
Looking Ahead: While Wall Street continues to ride the momentum from Nvidia's earnings, investors are bracing for the impact of inflation data and earnings reports from key retail players. The coming week will provide valuable insights into the state of the economy and the resilience of the market in the face of inflationary pressures. As investors navigate these uncertainties, a cautious yet optimistic approach may be warranted.
Weekly Calendar Wall Street
Monday
Economic data: Dallas Fed Manufacturing Activity, February (-27.4 previously); New home sales, January (684,000 annualized rate expected, 664,000 previously); New home sales, month-over-month, January (+3% expected, +8% previously)
Earnings: Domino's Pizza (DPZ), Freshpet (FRPT), Hims & Hers (HIMS), iRobot (IRBT), Workday (WDAY), Zoom (ZM)
Tuesday
Economic data: Conference Board Consumer Confidence, February (114.8 expected, 114.8 previously); S&P CoreLogic Case-Shiller, 20-City Composite home price index, month-over-month, December (+0.15% previously); S&P CoreLogic Case-Shiller 20-City Composite home price index, year-over-year, December (+5.4% previously)
Earnings: AutoZone (AZO), Beyond Meat (BYND), Cava (CAVA), Cracker Barrel (CBRL), Devon Energy (DVN), First Solar (FSLR), Lowe's (LOW), Macy's (M), Norwegian Cruise Line (NCLH)
Wednesday
Economic data: MBA Mortgage Applications, week ending Feb. 23 (-10.6% prior); Wholesale inventories month-over-month, January (+0.4% previously); Fourth quarter GDP, second estimate (+3.3% annualized rate expected, +3.3% previously); Fourth quarter personal consumption, second estimate (+2.7% annualized expected; +2.8% previously)
Earnings: Advance Auto Parts (AAP), AMC (AMC), Baidu (BIDU), C3.ai (AI), Icahn Enterprises (IEP), TJX Companies (TJX), Marathon Digital Holdings (MARA), Novavax (NVAX), Okta (OKTA), Paramount Global (PARA), Salesforce (CRM), Snowflake (SNOW), Weight Watchers (WW)
Thursday
Economic data: Initial jobless claims, week ended Feb. 24 (201,000 previously); Personal income, month-over-month, January (+0.5% expected, +0.3% previously); Personal spending, month-over-month, January (+0.2% expected, +0.7% previously); PCE inflation, month-over-month, January (+0.3% expected, +0.2% previously); PCE inflation, year-over-year, January (+2.4% expected, +2.6% previously); "Core" PCE, month-over-month, January (+0.4% expected, +0.2% previously); "Core" PCE, year-over-year, January (+2.8% expected; +2.9% previously)
Earnings: Anheuser Busch (BUD), Bath & Body Works (BBWI), Best Buy (BBY), Birkenstock (BIRK), Celsius (CELH), Dell (DELL), Fisker (FSR), Hewlett Packard Enterprises (HPE), Six Flags (SIX), SoundHound (SOUN), Zscaler (ZS)
Friday
Economic news: S&P Global US Manufacturing PMI, February final (51.5 previously); ISM manufacturing, February (49.2 expected, 49.1 previously); ISM prices paid, February (52.9 previously); University of Michigan consumer sentiment, February final (79.6 expected, 79.6 prior)
Earnings: FuboTV (FUBO), Plug Power (PLUG)
As Wall Street prepares for another eventful week, all eyes will be on inflation data and retail earnings reports. While the market remains buoyant following Nvidia's earnings high, investors will closely monitor economic indicators for signs of inflationary pressures and their potential impact on market sentiment. With volatility likely to persist, prudent risk management and strategic decision-making will be key for investors navigating the dynamic landscape of Wall Street.
NIST Graded Our Post-Quantum Cryptography. Zero Failures.
NIST's Algorithm Validation Test System generated test vectors nobody had seen, we answered them over the ACVP protocol, and NIST graded the result: 2,130 cases across ML-KEM, ML-DSA and SLH-DSA in every parameter set offered, zero failures, demo certificate A11025. This is what that proves, where we deliberately drew the claim narrower than NIST's own matrix, and why the FIPS 140-2 sunset on 21 September makes the distinction between being graded and grading yourself worth understanding.
The Problem Is Not the Problem
People treat the Jack Sparrow line as a joke. The attribution is a joke. The sentence is not. Forty years in markets says the same thing Epictetus said in 125 CE and Robert Merton named in 1948: the event is finite, and the story you appoint to govern it is not. This essay walks the quote back to its actual sources, draws the loop that turns a feeling into an order, and sets out the four places a rule written in advance cuts the loop. Faith is not a hedge. It is a stance.
What KXCO Is, and Why the Hard Problem Was Never Intelligence
The prevailing enthusiasm assumes the hard problem is intelligence. It is not. It is that banks, hospitals, courts and governments are being asked to let software act on their behalf with no way to establish who decided, on what basis, or whether the record will still read in a decade. KXCO founder Shayne Heffernan sets out the architecture that answers those questions, drawn as a graph, and argues that properly constructed AI is an amplifier of human judgement rather than a replacement for it.
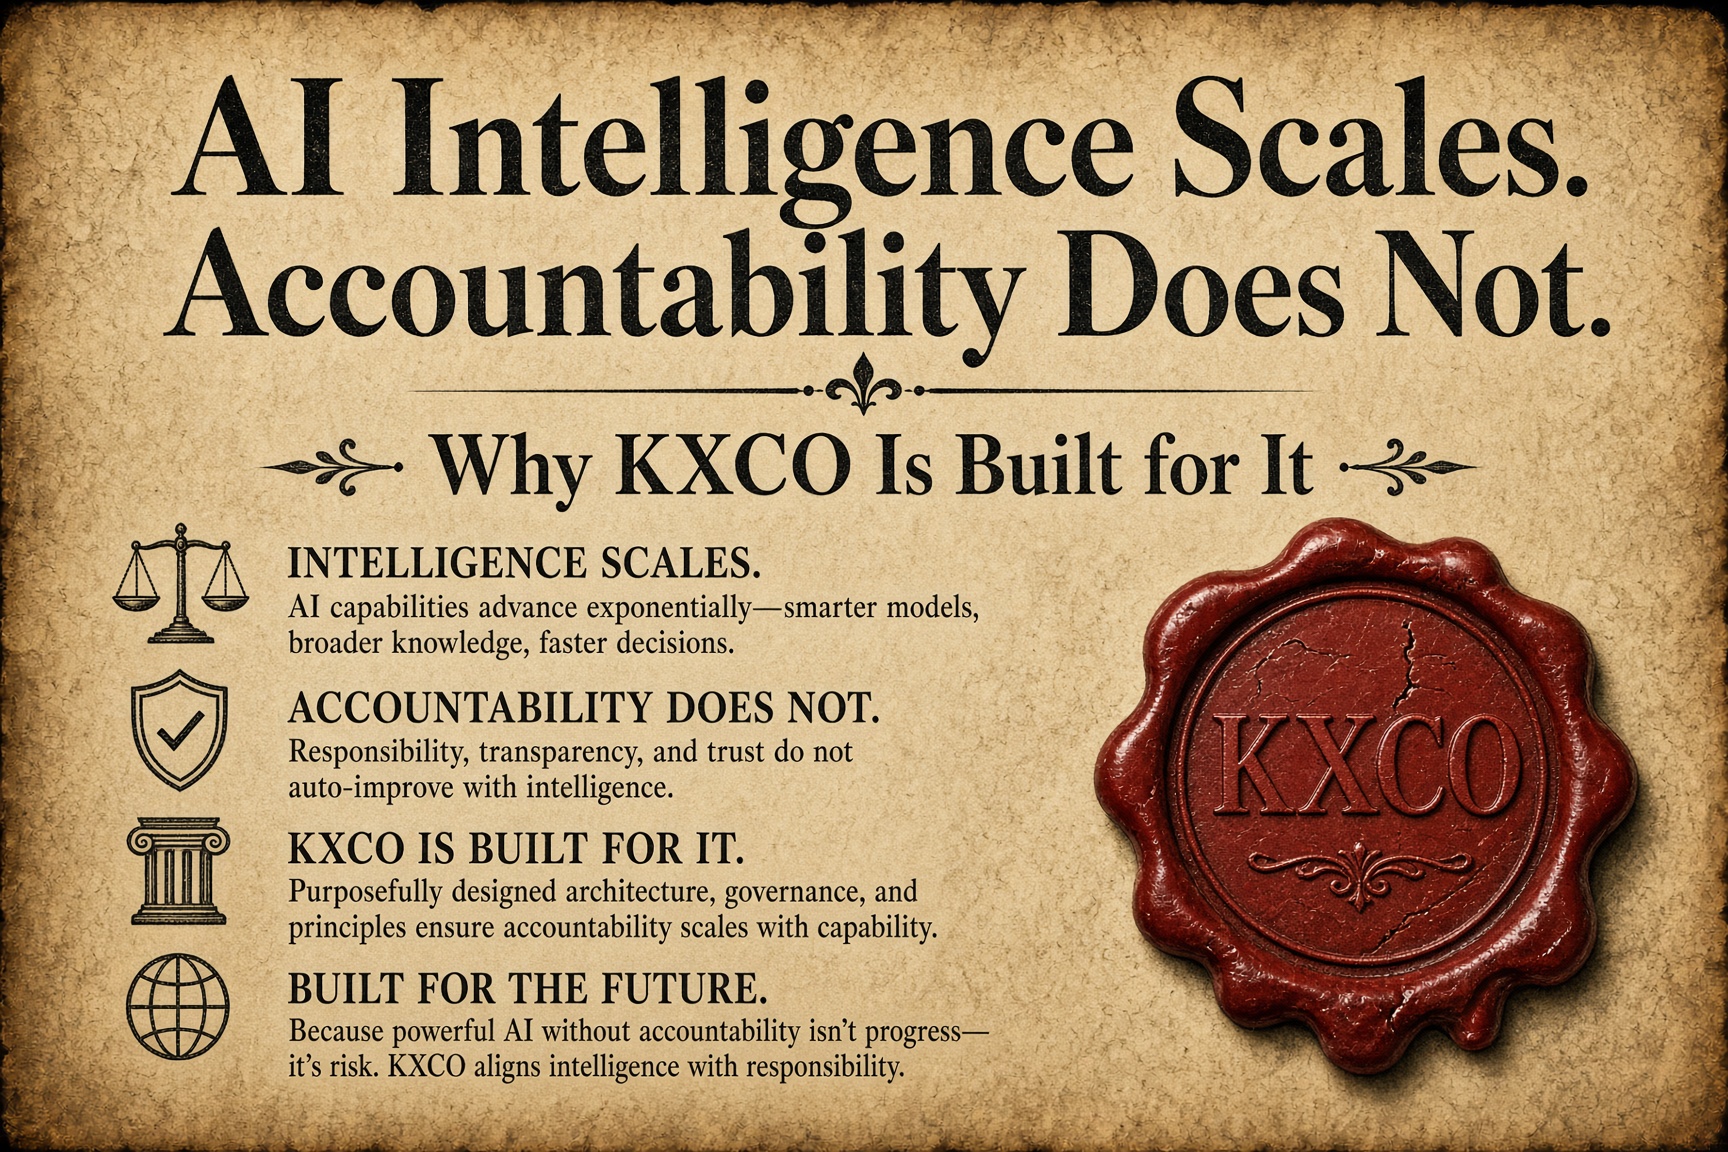
AI Intelligence Scales. Accountability Does Not. Why KXCO Is Built for It.
Capability is becoming abundant and everything abundant gets cheap. What does not get cheap is the person who has to sign, and they can only carry what they can see. Four conditions follow from that, and four independent authorities reached the first of them last month without knowing it.
Every story, signed and delivered.
Subscribe to the kxco channel and get the headline, the AI-written key takeaways, and the chain-anchor link the moment we publish. Audio versions and per-ticker subscriptions arrive in the next iteration.