
S&P/Experian Consumer Credit Default Indices
S&P Dow Jones Indices and Experian released today data through February 2021 for the S&P/Experian Consumer Credit Default Indices. The indices represent a comprehensive measure of changes in consumer credit defaults and show that the composite rate was five basis points higher at 0.53%. The bank card default rate rose 21 basis points to 2.93%. The auto loan default rate was down five basis points to 0.51% and the first mortgage default rate was up five basis points to 0.37%.

(PRNewsfoto/S&P Dow Jones Indices)
All five major metropolitan statistical areas ("MSAs") showed higher default rates compared to last month. The rate for New York increased 34 basis points to 0.83% while Miami rose 21 basis points to 1.16%. Los Angeles was 12 basis points higher at 0.44%. Chicago and Dallas were each up two basis points, to 0.55% and 0.59% respectively.
The table below summarizes the February 2021 results for the S&P/Experian Consumer Credit Default Indices. These data are not seasonally adjusted and are not subject to revision.
National Indices
Index
February 2021
Index Level
January 2021
Index Level
February 2020
Index Level
Composite
0.53
0.48
1.02
First Mortgage
0.37
0.32
0.84
Bank Card
2.93
2.72
3.41
Auto Loans
0.51
0.56
0.89
Source: S&P/Experian Consumer Credit Default Indices
Data through February 2021
The table below provides the index levels for the five major MSAs tracked by the S&P/Experian Consumer Credit Default Indices.
MSA
February 2021
Index Level
January 2021
Index Level
February 2020
Index Level
New York
0.83
0.49
1.00
Chicago
0.55
0.53
1.21
Dallas
0.59
0.57
1.02
Los Angeles
0.44
0.32
0.80
Miami
1.16
0.95
1.66
Source: S&P/Experian Consumer Credit Default Indices
Data through February 2021
For more information about S&P Dow Jones Indices, please visit www.spdji.com.
ABOUT THE S&P/EXPERIAN CONSUMER CREDIT DEFAULT INDICES
Jointly developed by S&P Dow Jones Indices LLC and Experian, the S&P/Experian Consumer Credit Default Indices are published on the third Tuesday of each month at 9:00 am ET. They are constructed to track the default experience of consumer balances in four key loan categories: auto, bankcard, first mortgage lien and second mortgage lien. The Indices are calculated based on data extracted from Experian's consumer credit database. This database is populated with individual consumer loan and payment data submitted by lenders to Experian every month. Experian's base of data contributors includes leading banks and mortgage companies, and covers approximately $11 trillion in outstanding loans sourced from 11,500 lenders.
For more information, please visit: www.spindices.com/indices/indicators/sp-experian-consumer-credit-default-composite-index.
ABOUT S&P DOW JONES INDICES
S&P Dow Jones Indices is the largest global resource for essential index-based concepts, data and research, and home to iconic financial market indicators, such as the S&P 500® and the Dow Jones Industrial Average®. More assets are invested in products based on our indices than products based on indices from any other provider in the world. Since Charles Dow invented the first index in 1884, S&P DJI has been innovating and developing across the spectrum of asset classes helping to define the way investors measure and trade the markets.
S&P Dow Jones Indices is a division of S&P Global (NYSE: SPGI), which provides essential intelligence for individuals, companies and governments to make decisions with confidence. For more information, visit www.spdji.com.
ABOUT EXPERIAN
Experian is the world's leading global information services company. During life's big moments – from buying a home or a car, to sending a child to college, to growing a business by connecting with new customers – we empower consumers and our clients to manage their data with confidence. We help individuals to take financial control and access financial services, businesses to make smarter decisions and thrive, lenders to lend more responsibly, and organizations to prevent identity fraud and crime.
We have 17,800 people operating across 45 countries and every day we're investing in new technologies, talented people and innovation to help all our clients maximize every opportunity. We are listed on the London Stock Exchange (EXPN) and are a constituent of the FTSE 100 Index.
NIST Graded Our Post-Quantum Cryptography. Zero Failures.
NIST's Algorithm Validation Test System generated test vectors nobody had seen, we answered them over the ACVP protocol, and NIST graded the result: 2,130 cases across ML-KEM, ML-DSA and SLH-DSA in every parameter set offered, zero failures, demo certificate A11025. This is what that proves, where we deliberately drew the claim narrower than NIST's own matrix, and why the FIPS 140-2 sunset on 21 September makes the distinction between being graded and grading yourself worth understanding.
The Problem Is Not the Problem
People treat the Jack Sparrow line as a joke. The attribution is a joke. The sentence is not. Forty years in markets says the same thing Epictetus said in 125 CE and Robert Merton named in 1948: the event is finite, and the story you appoint to govern it is not. This essay walks the quote back to its actual sources, draws the loop that turns a feeling into an order, and sets out the four places a rule written in advance cuts the loop. Faith is not a hedge. It is a stance.
What KXCO Is, and Why the Hard Problem Was Never Intelligence
The prevailing enthusiasm assumes the hard problem is intelligence. It is not. It is that banks, hospitals, courts and governments are being asked to let software act on their behalf with no way to establish who decided, on what basis, or whether the record will still read in a decade. KXCO founder Shayne Heffernan sets out the architecture that answers those questions, drawn as a graph, and argues that properly constructed AI is an amplifier of human judgement rather than a replacement for it.
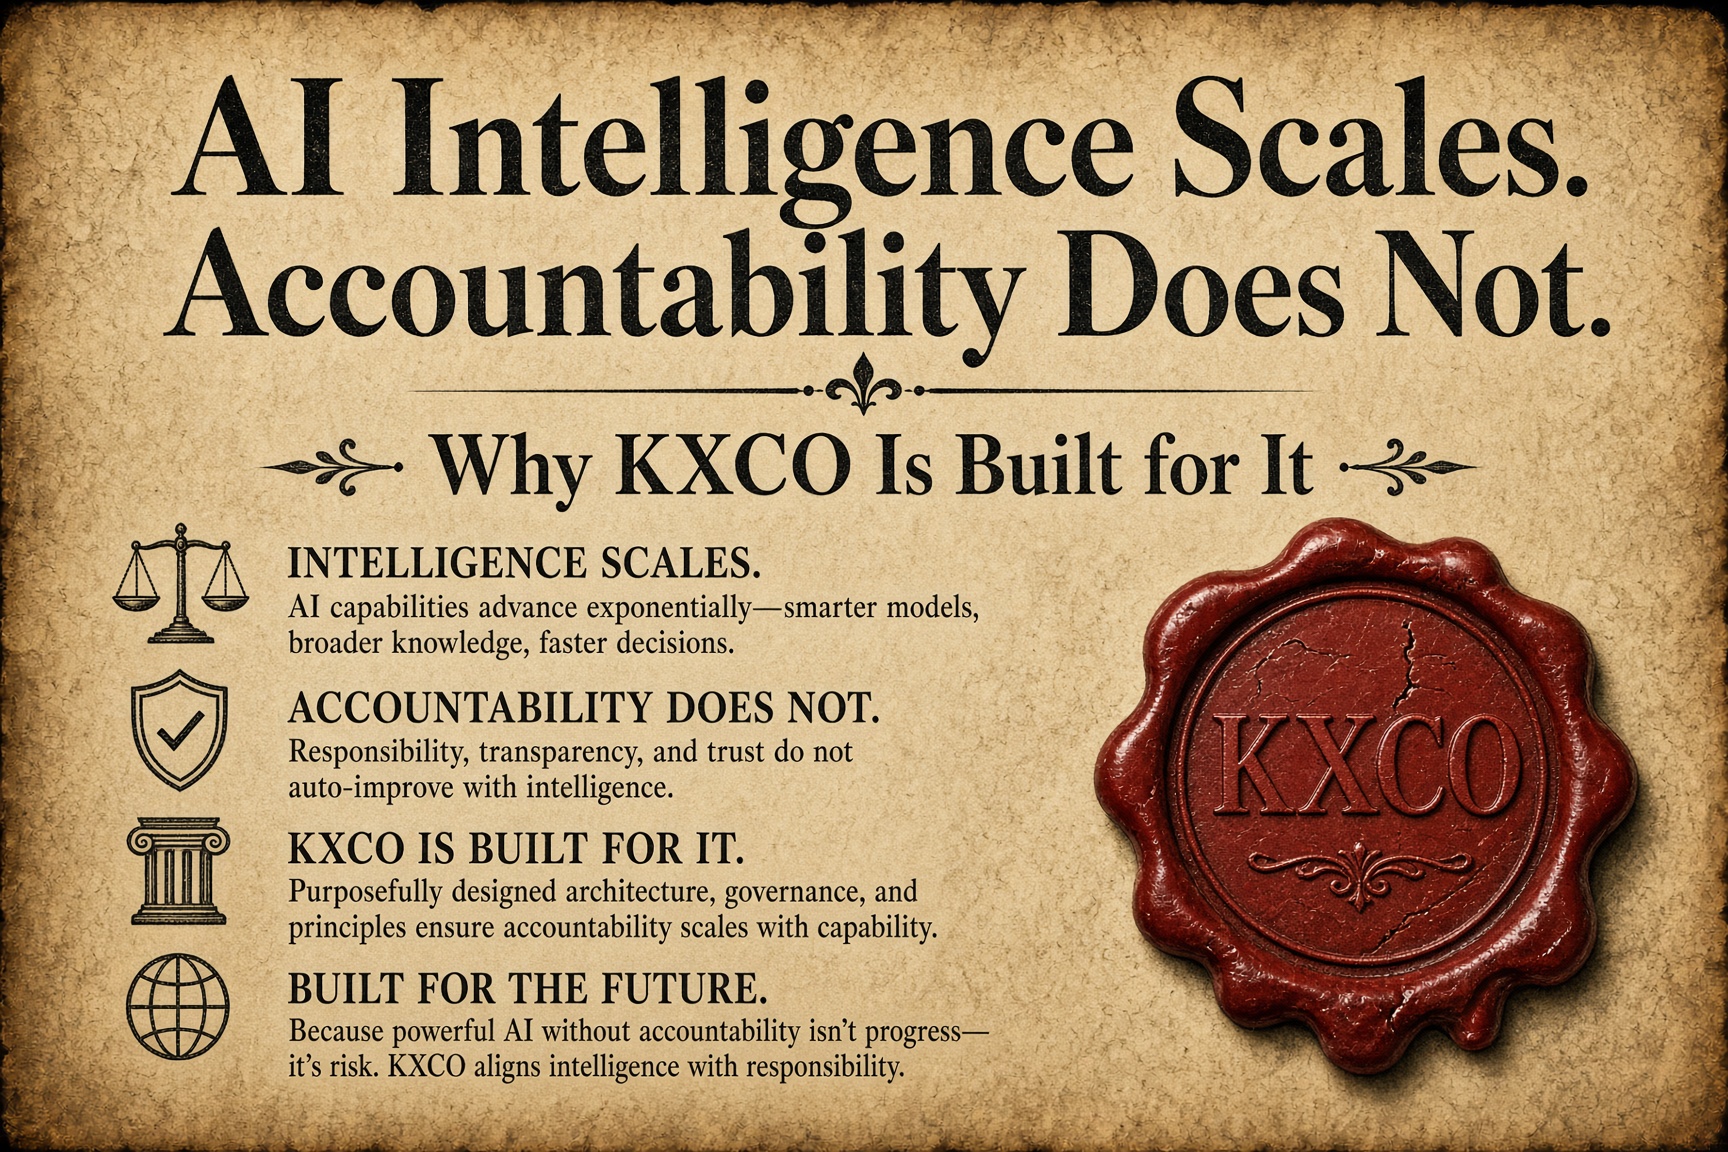
AI Intelligence Scales. Accountability Does Not. Why KXCO Is Built for It.
Capability is becoming abundant and everything abundant gets cheap. What does not get cheap is the person who has to sign, and they can only carry what they can see. Four conditions follow from that, and four independent authorities reached the first of them last month without knowing it.
Every story, signed and delivered.
Subscribe to the kxco channel and get the headline, the AI-written key takeaways, and the chain-anchor link the moment we publish. Audio versions and per-ticker subscriptions arrive in the next iteration.