
Gold Price 2026: Supply & Demand Analysis
$NEM $AEM $GOLD $AU $GFI $KGC $NST
Part of theMacro Center
Gold Price 2026: Top Central Bank Holders, Leading Producers, Supply & Demand Analysis
The companies covered in the producers table are $NEM for Newmont, $AEM for Agnico Eagle Mines, $GOLD for Barrick Gold, $AU for AngloGold Ashanti, $GFI for Gold Fields, $KGC for Kinross Gold, and $NST for Northern Star Resources.
Gold remains one of the world’s most enduring stores of value and monetary assets. In 2025–2026, the gold price reached repeated all-time highs amid record central bank accumulation, resilient investment demand, geopolitical fragmentation, and persistent questions around fiat currency dominance and inflation hedging.
This comprehensive analysis examines everything about gold supply and demand, the top central bank gold holders with their buy/sell movements over the last three years and total reserves, the top corporate gold producers in a detailed table (annual output, total unmined reserves, and ticker), and the top 10 countries driving gold buying, imports, and production dynamics. All data is cross-verified from World Gold Council (WGC), IMF International Financial Statistics, USGS, company reports, and Metals Focus as of Q1 2026.
Gold Supply Fundamentals
Global gold supply comes primarily from mine production (~3,300 tonnes in 2024, with similar levels into 2025) plus recycling, with minor net producer hedging/de-hedging.
Mine production is geographically dispersed but concentrated among a few nations. China has led for years (~380 tonnes in 2024/2025, ~10–11% of global total). Russia (~310–330 t), Australia (~284–320 t), Canada (~200–202 t), and the United States (~158–160 t) round out the top tier. Other significant producers include Ghana, Mexico, Indonesia, Peru, and Uzbekistan.
Total above-ground gold stocks exceed 200,000–210,000 tonnes historically mined, with central banks holding roughly 17–20% (~36,000+ tonnes officially reported). Recycling supply is highly price-elastic; higher gold prices in 2025 boosted old jewelry and scrap flows. In Q1 2026 alone, recycling reached 366 tonnes (+5% y/y).
New mine supply faces structural headwinds: declining ore grades, rising costs, permitting delays, ESG pressures, and capital discipline among major producers. This limited responsiveness supports higher equilibrium gold prices over the medium term.
Gold Demand Fundamentals
Gold demand is diverse and resilient:
Jewelry (~45–50% of identifiable demand historically): Culturally dominant in India, China, Turkey, and the Middle East. Price-sensitive but supported by rising middle classes and gifting traditions.
Investment (bars, coins, ETFs): Strong safe-haven bid during uncertainty. ETFs like SPDR Gold Shares (GLD) represent one of the largest single non-official holders globally.
Central banks & official institutions: The standout driver since 2022. Net purchases exceeded 1,000 tonnes in multiple recent years (2025 ~863 tonnes reported, with broader estimates higher).
Technology/Industrial (~7–10%): Electronics, dentistry, aerospace, and emerging uses. Relatively price-inelastic.
Other/OTC: Includes institutional and high-net-worth flows not captured in reported categories.
In 2025, total gold demand (including OTC) topped 5,000 tonnes amid 53 all-time price highs. Q1 2026 demand remained robust at ~1,231 tonnes.
Supply-Demand Balance and Gold Price Impact
When demand outstrips visible supply (as seen with sustained central bank buying + investment), prices rise to ration physical metal and incentivize recycling while curbing jewelry offtake. The 2022–2025 period featured persistent structural demand support from de-dollarization trends, sanctions resilience (gold has no counterparty risk), and portfolio diversification by emerging market central banks.
Gold’s low correlation to equities and bonds, negative correlation to real yields in certain regimes, and role as a hedge against currency debasement and geopolitical risk have reinforced its monetary premium. Record central bank buying has been particularly price-supportive because it is strategic and less price-sensitive than private investment or jewelry.
Top Central Bank Gold Holders and Buy/Sell Movements (Last 3 Years)
Central banks collectively hold the largest concentrated official gold reserves. Data from WGC and IMF (as of Q1 2026 or latest reported):
Top Holders (approximate tonnes, latest available):
United States — 8,133.46 t (stable for decades; no material buy/sell activity; ~70%+ of reserves in gold).
Germany — ~3,350 t (largely stable post-repatriation; minor adjustments).
Italy — 2,451.84 t (stable).
France — ~2,437 t (stable).
Russia — ~2,327 t (occasional net sales in 2025–2026 periods amid other priorities).
China (People’s Bank of China) — 2,313.46 t official (continued steady buying over 18+ consecutive months into 2026; actual holdings widely believed higher; significant accumulation over last 3 years despite opaque reporting).
Switzerland — ~1,040 t (stable; key refining hub).
India — ~880 t (steady RBI purchases; notable increase over last 3 years).
Japan — ~846 t (stable).
Netherlands / Poland / others — Poland has risen rapidly to ~582 t (one of the largest buyers globally in recent years).
Notable movements last 3 years (2023–2025/early 2026):
Poland (National Bank of Poland): Largest or near-largest reported buyer in multiple periods; added ~100+ t in 2025 alone, with strong cumulative gains targeting higher gold % of reserves (~30% goal). Major driver of EM accumulation narrative.
China: Consistent net buyer (reported increments + estimated larger flows); part of multi-year diversification.
India: Steady additions by RBI; cumulative meaningful increase supporting ~880 t level.
Turkey, Kazakhstan, Uzbekistan, Czech Republic, Brazil: Active buyers in various quarters; broadening buyer base.
Russia: Periodic net sales offsetting some gains elsewhere.
Western Europe & US: Largely stable holders with minimal flows.
Overall: Central banks added hundreds of tonnes net annually in recent years, with 2025 still robust (~863 t reported) despite slightly lower than peak prior years.
This shift toward emerging market accumulation (now ~32% of global official reserves vs. 18% in 2000) reflects strategic de-risking from traditional reserve currencies and assets.
Leading Gold Mining Companies: Corporate Producers
Here is a fact-checked ranking of leading gold mining companies based on 2025 attributable production (tonnes), proven & probable (P&P) mineral reserves, and ticker symbol. Data compiled from company reports, INN, and industry sources.
Top Gold Mining Companies – 2025 Production, Reserves & Ticker
Rank | Company | Country | 2025 Output (tonnes) | P&P Reserves (Moz) | Ticker |
|---|---|---|---|---|---|
1 | Newmont Corporation | USA | 183.17 | 118.2 | NEM |
2 | Agnico Eagle Mines | Canada | 107.23 | Large (multi-decade mine life) | AEM |
3 | Barrick Gold | Canada | 101.24 | 85.0 | GOLD |
4 | Navoi Mining & Metallurgy | Uzbekistan | 97.98 | Very large (Muruntau & others) | N/A (State) |
5 | Zijin Mining Group | China | Strong growth (~80+ est.) | Significant | 2899.HK |
6 | AngloGold Ashanti | South Africa | Strong growth | 36.5 (2025) | AU |
7 | Polyus | Russia | Significant | 101.0 | PLZL.ME |
8 | Gold Fields | South Africa | Competitive | Substantial | GFI |
9 | Kinross Gold | Canada | Solid mid-tier | Material | KGC |
10 | Northern Star Resources | Australia | Growing | Substantial | NST.AX |
Key observations: Newmont maintains the largest reserve base and production scale despite portfolio optimization and divestments. Barrick and Agnico Eagle deliver high-quality, lower-risk production. State-linked producers (Navoi, Zijin, Polyus) add meaningful supply but with varying transparency and geopolitical considerations. The industry is consolidating; M&A and brownfield expansions are key to offsetting depletion.
Longer-term, declining grades and higher sustaining costs across the sector act as a structural floor for the gold price.
Top 10 Countries That Buy Gold: Imports, Production & Dynamics
Gold “buying” encompasses central bank accumulation, jewelry fabrication/import, investment bars/coins, and industrial offtake. Top players blend these:
India — World’s largest gold consumer/jewelry market. Low domestic mine production; heavy importer (hundreds of tonnes annually for jewelry + investment + RBI central bank buying). Cultural and investment demand dominant.
China — Top global producer (~380 t) yet still significant net buyer via central bank accumulation + strong jewelry/industrial demand. Domestic production meets much but not all needs.
United States — Major investment demand via ETFs and bars/coins; modest mine production (~158–160 t). Net importer for consumption/investment.
Switzerland — Top importer by value (refining & redistribution hub); re-exports globally. Low domestic production.
United Kingdom / Hong Kong — Key trading and refining hubs with significant import volumes for onward distribution.
Turkey — Major jewelry consumer + active central bank buyer in recent years.
Poland — Standout central bank accumulator (rapid reserve growth last 3 years); limited mine production.
Russia — Major producer but with periods of central bank sales or adjusted flows; domestic focus.
Uzbekistan / Kazakhstan — Significant producers with active central bank buying (high % of reserves in gold for some).
Germany / Italy / France — Large stable holders with minimal recent flows; some jewelry/industrial demand.
Import vs. Production dynamics: India and many Western nations are structural net importers. China balances high production with high internal demand and official buying. Central Asian and some EM nations combine meaningful production with reserve-building strategies. Switzerland and UK function as entrepôt hubs rather than final consumers.
Gold Price Outlook & Strategic Implications
Key gold price drivers heading into late 2026 and beyond:
Central bank demand trajectory (expected to remain supportive though possibly moderating from peaks).
Real yields, USD strength, and monetary policy divergence.
Geopolitical risk premium and de-dollarization flows.
ETF and private investment sentiment (sensitive to price and macro backdrop).
Mine supply constraints and cost inflation.
Jewelry demand elasticity in key Asian markets.
Structural tailwinds (central bank diversification, limited new mine supply, gold’s monetary attributes) suggest a higher-for-longer price environment compared to pre-2022 norms, with volatility around macro data and risk events. Gold continues to serve as portfolio insurance and a hedge against systemic uncertainties.
Conclusion Gold’s role as a strategic reserve asset has been powerfully reaffirmed by central bank behavior over the last three years. Combined with constrained mine supply growth and diverse private demand, the metal is well-positioned within a multi-polar financial system. Investors, institutions, and policymakers monitoring the gold price should focus on central bank flows, ETF positioning, and the supply-side cost curve as primary indicators.
For real-time gold price tracking, production updates, and institutional flows, refer to verified sources such as the World Gold Council.
Data verified as of June 2026 from WGC, IMF, USGS, company filings, and industry analysts. Gold markets evolve rapidly; always cross-reference latest reports.
The Heirloom Foods
Heirloom foods are the working memory of agriculture. Open-pollinated plants and landrace animals that families, villages and seed savers kept because they tasted better, survived drought or frost, or simply refused to disappear. This is a map of that pantry: the ancient and heritage wheats, the sourdough cultures older than commercial yeast, the vegetables that refused to modernize, and the oldest surviving livestock breeds, with an honest account of what is known and not known about health.
Frequencies and Thinking
Thinking is not a metaphor sitting on top of frequency. It is frequency, organised, across four layers that are electrical, chemical, physical and biological. A companion to The Invisible Symphony that ranks frequency pollution by the quality of the human data behind it, noise first and radiofrequency third, then turns to the part you control: what education, exercise, blood pressure, hearing, sleep, diet and purpose have actually proved about cognitive longevity.
Earnings, the Economic Calendar and Trading Strategies: September 8 to 12, 2026
A four-session week decides more than a print. Oracle reports after the close on Thursday 10 September, PPI lands that morning and CPI on Friday, with the ECB in between and the FOMC eight days out. Oracle is the last hyperscaler of the cycle and the widest value gap on the KXCO Ontology Live Analyst Outlook layer: a $457bn market value under a $638bn contracted backlog. Here is the calendar, the graph behind it, the levels and the book.
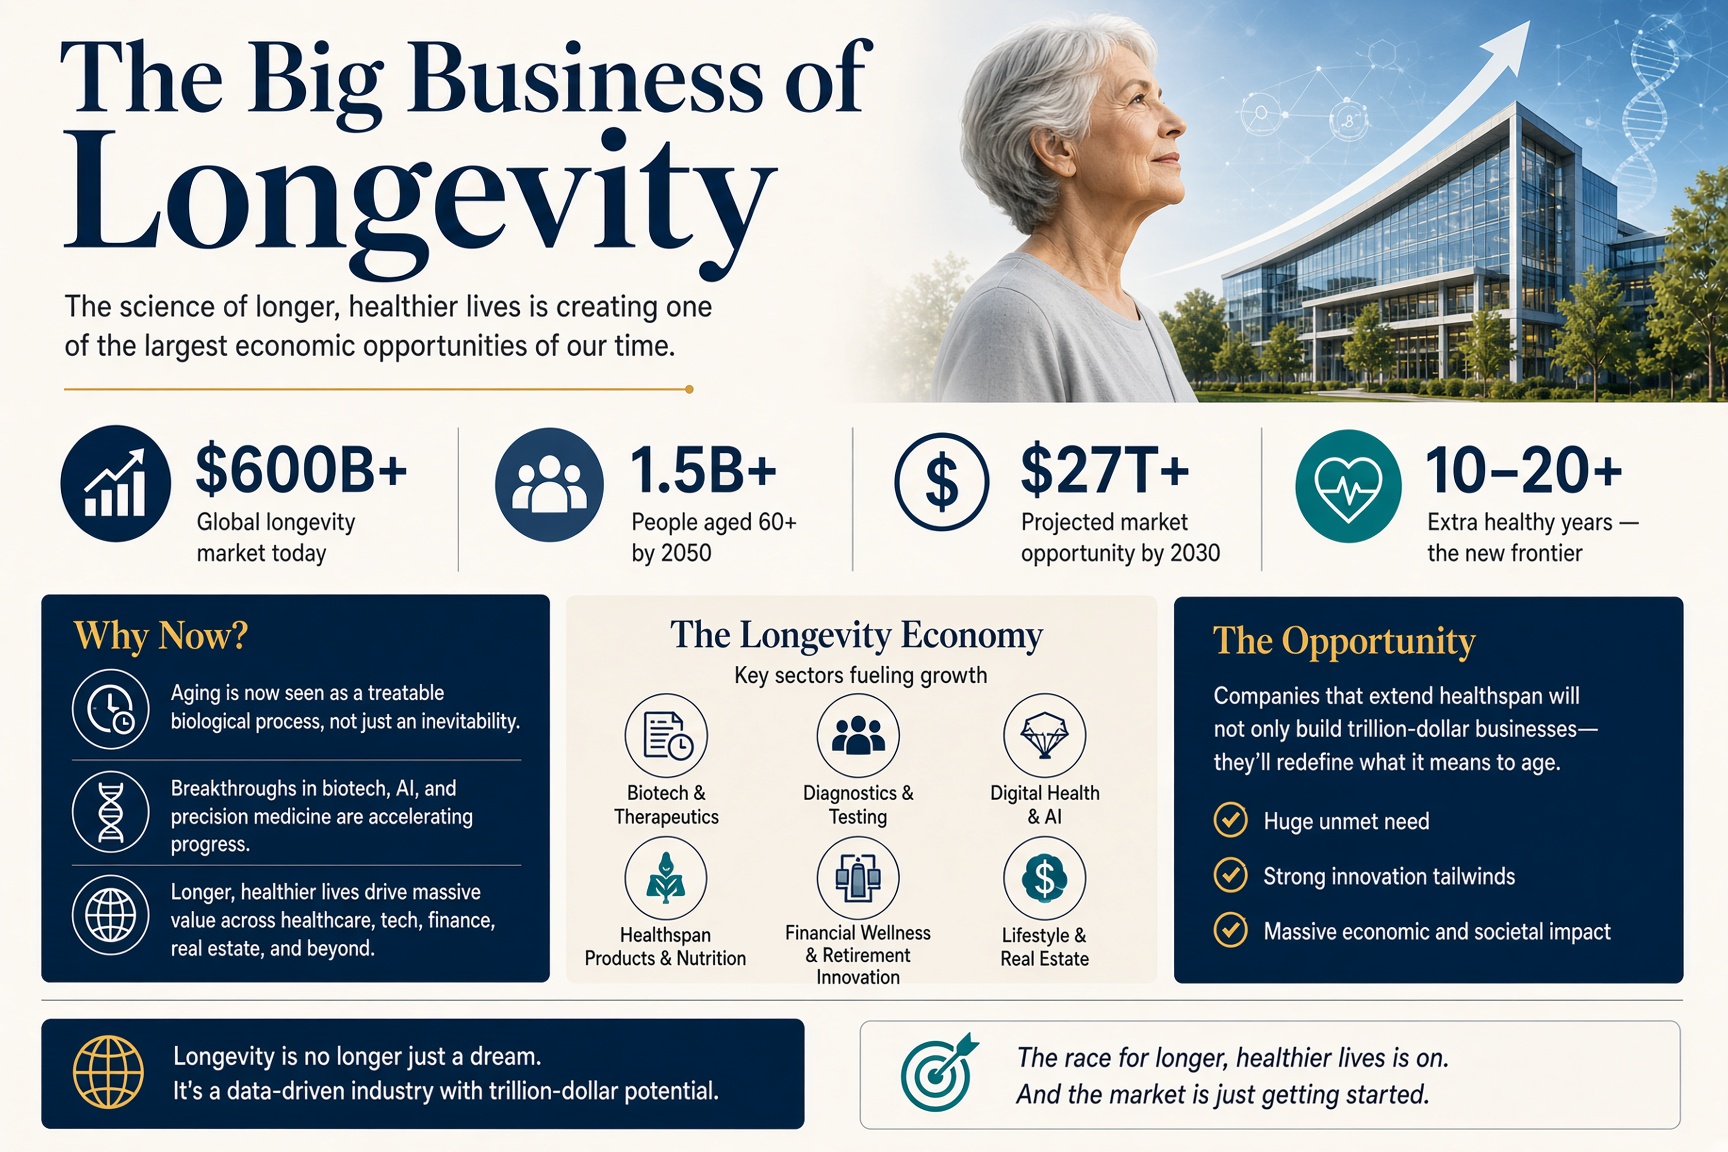
The Big Business of Longevity
Eight molecules carry an FDA label. Six carry a nonbinding committee vote. The gray market sells the second as though it were the first. A field report on the longevity pipeline, the capital behind it, and the listed names that matter.
Every story, signed and delivered.
Subscribe to the kxco channel and get the headline, the AI-written key takeaways, and the chain-anchor link the moment we publish. Audio versions and per-ticker subscriptions arrive in the next iteration.