
Equity Market Outlook
For equity markets, it has been yet another remarkable month. Big tech was once more the main engine, even although US consumption showed some slowing down. A run of economic data presently points to a slowing down in US economic activity; moreover, the disinflation process has started to somewhat revive prospects for a lower borrowing cost by year end.
While the Nasdaq 100 and Dow are up +6.28% and +1.14% respectively, the S&P 500 is up +3.80% MTD. The NYSE's percentage is -0.50%.
Political concern about France's approaching Sunday parliamentary election caused great volatility in European equity markets. Declining -3.58% this month, France's CAC 40 index fared worst among European indexes. This change in attitude seems to be general since performance of European stocks has been less than that of US peers.
Yields in the bond market have dropped throughout Europe as well as the US. Closely related to the Fed Funds rate, the yield on the 2-year US Treasury note dropped from 4.94% in May to 4.74%. From May's 4.56%, the benchmark 10-year US Treasury note yield dropped to 4.23%; the 30-year bond yield dropped from 4.70% to 4.36%. The 10-year German bunds yield in Europe have dropped by -21.8 basis points (bps), while the UK 10-year yield dropped by -18.2 bps.
The Economic Future
With the US economy adding about 272,000 jobs in May, the labor market there shows indications of deceleration. From 3.9% in April to 4.0% in May, the unemployment rate climbed to 4.0%—its first time rising since January 2021. Importantly for the Fed, the labor force participation rate dropped from 62.7% to 62.5%, suggesting a declining fraction of people either employed or actively looking for work. While "real" average hourly earnings (adjusted for inflation) grew by 0.8%, up from April's 0.5%, average hourly earnings in May 2023 grew by 4.1% y/o/y. Usually regarded as in line with the Fed's 2% inflation target, wage increase falls between 3.0% and 3.5%.
May's inflation rate dropped to 3.3% y/o/y, slightly below April's 3.4%, signifying the second straight month of declining inflation. Reduced gas prices helped explain some of this drop. Still, shelter prices kept on their increasing trend, gaining 2.0% for the fourth straight month.
Indices of consumer mood pointed to a small drop in confidence. From 102.0 in May, the consumer confidence index of the Conference Board fell to 100.4 in June. Moreover, the consumer mood index of the University of Michigan dropped for the third straight month, falling to 65.6 in June 2024, from 69.1 in May. From 69.6, the present conditions dropped to 62.5; the expectations sub index dropped from 68.8 to 67.6. Year-ahead inflation predictions stayed constant at 3.3%; the five-year projection moved up to 3.1% from 3%.
Rising to 54.6 from May's 54.5, the flash Composite PMI Output Index hit a 26-month high. The services industry drove much of this increase; the S&P Global flash index for service providers rose 0.3 points to 55.1, its highest level since April of 2022. Reaching 51.7 from May's 51.2, the manufacturing flash PMI likewise rose, setting a 3-month high.
The timing of the ECB second interest rate cut is unknown; money markets price in 58 basis points (bps) of easing in 2024. This implies two cuts are predicted, with a roughly thirty% chance of a third by year-end. Though Olli Rehn, Governor of the Bank of Finland, suggests that borrowing expenses could reach as low as 2.25%-2.50% in 2025, ECB officials have differing views on the topic.
Though a declining trend is expected to continue in the following year, with inflation matching the target by the end of 2025, the ECB's inflation projection shows a continuous overshoot of its 2% target for the remainder of 2024. Though the eurozone unemployment rate dropped somewhat to 6.40%, pay pressures remain a cause of concern. This is noteworthy in view of the annual inflation rate of the euro area, which climbed from 2.4% in April to 2.6% in May 2024.
May's inflationary pressures in the UK kept lowering; the headline rate dropped from April's 2.3% year-on-year to 2.0% year-on-year, so attaining its lowest level since July 2021. While core inflation came at 3.5%, services prices stayed high at 5.7%. Concurrently, average salaries stayed constant at 6.0%, in line with the preceding three-month period; unemployment crept up to 4.4% from 4.3%. At 5.9%, the annual increase in employees' average total compensation—including bonuses—also stayed the same.
The S&P Global flash Composite PMI for June dropped to 51.7, from May's 53.0 and indicated a seven-month low on the front of expansion. Also a seven-month low, the flash services PMI similarly dropped to 51.2 from 52.9 in May. Still, the GfK Consumer Confidence Survey shows that consumer mood is improving; the confidence index rose to -14 in June, a three-point increase from May. Three measures especially improved, one dropped, and one stayed the same from the announcement last month. Following a little rebound in May, retail sales volumes fell in the year before June.
Emphasizing the need of tight monetary policy to lower inflation, the BoE kept interest rates at 5.25% noting a "finely balanced" decision by some of the nine members on the Monetary Policy Committee. As price pressure releases and inflation falls, markets are pricing in a higher than 50% chance of a rate change in August. Though headline inflation is declining, service sector costs remain high.
Given the rather low unemployment rate and earnings still outpacing inflation, the economy may not be as of a major concern as the UK gets ready for a general election on July 4. Still, expected are tax hikes and budget cuts regardless of the party that wins the election.
NIST Graded Our Post-Quantum Cryptography. Zero Failures.
NIST's Algorithm Validation Test System generated test vectors nobody had seen, we answered them over the ACVP protocol, and NIST graded the result: 2,130 cases across ML-KEM, ML-DSA and SLH-DSA in every parameter set offered, zero failures, demo certificate A11025. This is what that proves, where we deliberately drew the claim narrower than NIST's own matrix, and why the FIPS 140-2 sunset on 21 September makes the distinction between being graded and grading yourself worth understanding.
The Problem Is Not the Problem
People treat the Jack Sparrow line as a joke. The attribution is a joke. The sentence is not. Forty years in markets says the same thing Epictetus said in 125 CE and Robert Merton named in 1948: the event is finite, and the story you appoint to govern it is not. This essay walks the quote back to its actual sources, draws the loop that turns a feeling into an order, and sets out the four places a rule written in advance cuts the loop. Faith is not a hedge. It is a stance.
What KXCO Is, and Why the Hard Problem Was Never Intelligence
The prevailing enthusiasm assumes the hard problem is intelligence. It is not. It is that banks, hospitals, courts and governments are being asked to let software act on their behalf with no way to establish who decided, on what basis, or whether the record will still read in a decade. KXCO founder Shayne Heffernan sets out the architecture that answers those questions, drawn as a graph, and argues that properly constructed AI is an amplifier of human judgement rather than a replacement for it.
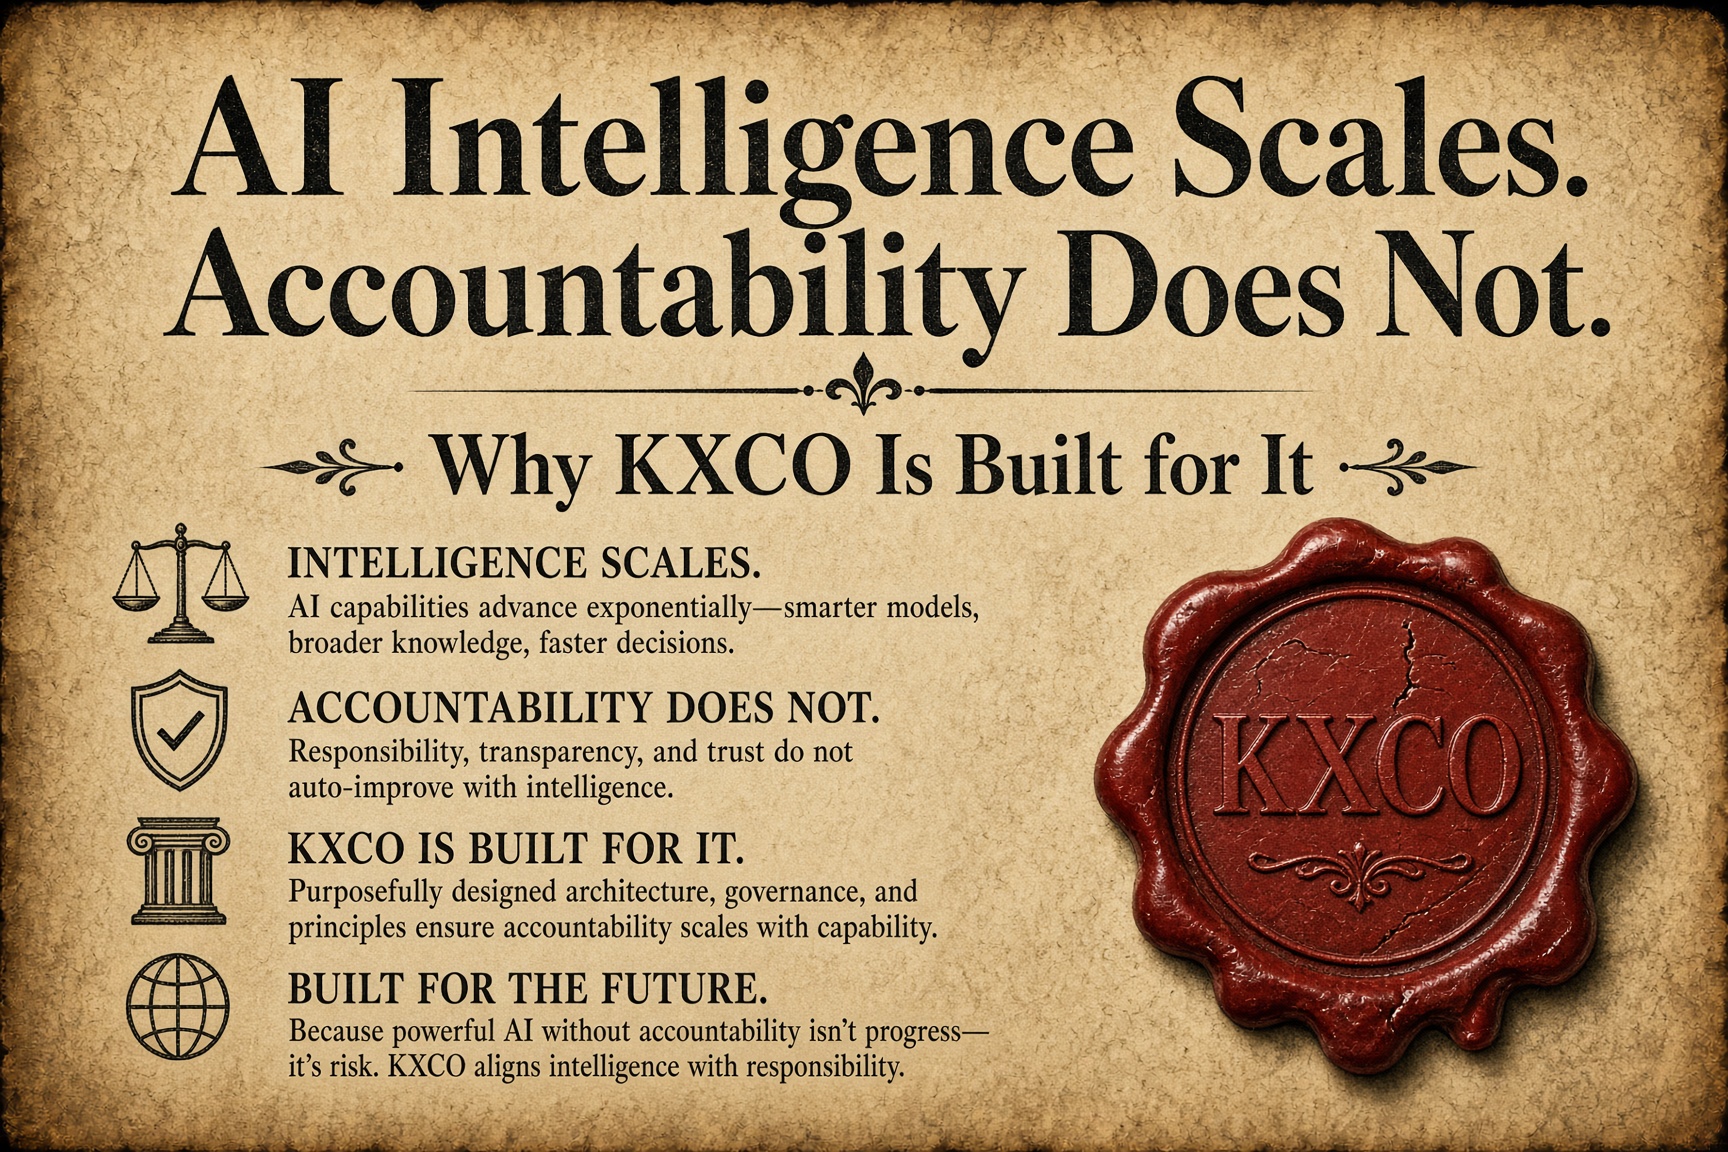
AI Intelligence Scales. Accountability Does Not. Why KXCO Is Built for It.
Capability is becoming abundant and everything abundant gets cheap. What does not get cheap is the person who has to sign, and they can only carry what they can see. Four conditions follow from that, and four independent authorities reached the first of them last month without knowing it.
Every story, signed and delivered.
Subscribe to the kxco channel and get the headline, the AI-written key takeaways, and the chain-anchor link the moment we publish. Audio versions and per-ticker subscriptions arrive in the next iteration.