
Dividend Diamonds in the Rough $VZ $T $CVX
Despite a lackluster 2023 for dividend stocks, Knightsbridge sees potential for a comeback in the coming year. While the S&P 500 soared 21%, high-yielding dividend stocks like the "Dogs of the Dow" languished, lagging behind the market and raising questions about their future appeal.
The Case for Caution:
Rising Interest Rates: In 2023, soaring interest rates made risk-free options like 10-year Treasuries with 5% yields more attractive compared to dividend stocks.
Dividend Underperformance: The SPDR Portfolio S&P 500 High Dividend ETF (SPYD) barely moved, negating its 4.8% dividend yield.
Widening Performance Gap: S&P 500 non-dividend stocks outperformed dividend-paying counterparts by a significant margin.
Knightsbridge's Counterpoint:
Yields Falling: Recent declines in yields could reignite interest in dividend ETFs offering income and potential capital appreciation.
Opportunity in the Dow's Dogs: Five specific "Dogs" – Altria Group (MO), Walgreens Boots Alliance (WBA), Verizon Communications (VZ), AT&T (T), and Chevron (CVX) – are predicted to rise 10% or more in 2024, on top of their already attractive 6%+ dividend yields.
Chevron: The Alpha Dog: Analysts believe Chevron, with its 4.2% yield and 26% potential upside, could be the star performer among the "Dogs."
Beyond Individual Stocks:
Dividend ETFs for Diversification: Knightsbridge recommends diversifying risk with ETFs like the SPDR Portfolio S&P 500 High Dividend ETF (SPYD) (4.8% yield) or ALPS Sector Dividend Dogs (SDOG) (4.3% yield).
Covered Call ETFs: An Alternative Income Stream: For investors seeking higher income, Knightsbridge highlights covered call ETFs like JPMorgan Equity Premium Income ETF (JEPI) (11.7% yield) and Amplify CWP Enhanced Dividend Income ETF (DIVO) (4.8% yield). These offer downside protection while generating income through covered call strategies.
**Company Symbol
Dividend Yield**
3M Company MMM
3.80%
Amgen Inc. AMGN
2.80%
Chevron Corporation CVX
4.20%
Coca-Cola Company KO
2.80%
Dow Inc. DOW
2.20%
Exxon Mobil Corporation XOM
3.70%
Honeywell International Inc. HON
2.30%
Johnson & Johnson JNJ
2.70%
JPMorgan Chase & Co. JPM
2.80%
Merck & Co., Inc. MRK
2.90%
Nike Inc. NKE
1.30%
Pfizer Inc. PFE
3.10%
Procter & Gamble Company PG
2.40%
The Travelers Companies Inc. TRV
3.60%
UnitedHealth Group Incorporated UNH
1.40%
Verizon Communications Inc. VZ
6.50%
Walgreens Boots Alliance Inc. WBA
5.30%
Knightsbridge's Takeaway:
While past performance doesn't guarantee future results, the potential for a rebound in dividend stocks, particularly select "Dogs of the Dow" and strategic ETF choices, shouldn't be ignored. Knightsbridge encourages investors to consider their risk tolerance and income goals when making dividend-focused investment decisions in this evolving market landscape.
NIST Graded Our Post-Quantum Cryptography. Zero Failures.
NIST's Algorithm Validation Test System generated test vectors nobody had seen, we answered them over the ACVP protocol, and NIST graded the result: 2,130 cases across ML-KEM, ML-DSA and SLH-DSA in every parameter set offered, zero failures, demo certificate A11025. This is what that proves, where we deliberately drew the claim narrower than NIST's own matrix, and why the FIPS 140-2 sunset on 21 September makes the distinction between being graded and grading yourself worth understanding.
The Problem Is Not the Problem
People treat the Jack Sparrow line as a joke. The attribution is a joke. The sentence is not. Forty years in markets says the same thing Epictetus said in 125 CE and Robert Merton named in 1948: the event is finite, and the story you appoint to govern it is not. This essay walks the quote back to its actual sources, draws the loop that turns a feeling into an order, and sets out the four places a rule written in advance cuts the loop. Faith is not a hedge. It is a stance.
What KXCO Is, and Why the Hard Problem Was Never Intelligence
The prevailing enthusiasm assumes the hard problem is intelligence. It is not. It is that banks, hospitals, courts and governments are being asked to let software act on their behalf with no way to establish who decided, on what basis, or whether the record will still read in a decade. KXCO founder Shayne Heffernan sets out the architecture that answers those questions, drawn as a graph, and argues that properly constructed AI is an amplifier of human judgement rather than a replacement for it.
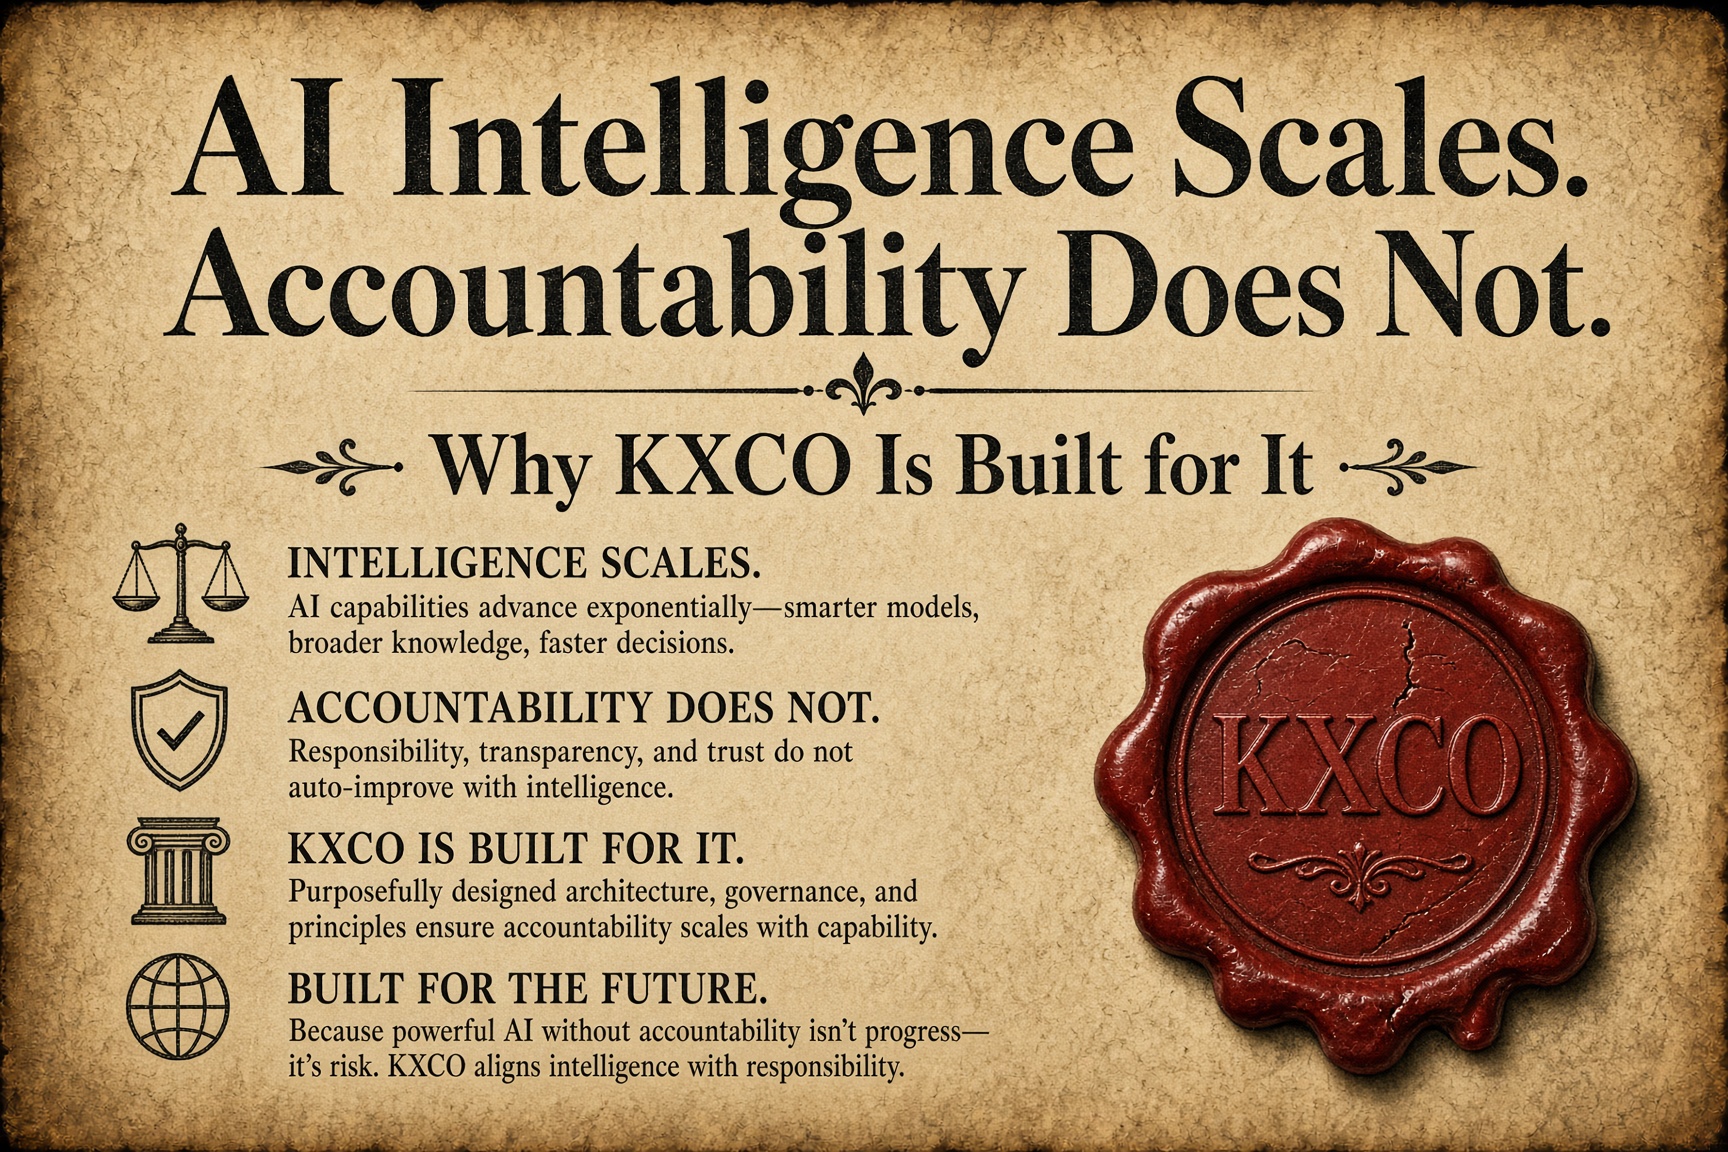
AI Intelligence Scales. Accountability Does Not. Why KXCO Is Built for It.
Capability is becoming abundant and everything abundant gets cheap. What does not get cheap is the person who has to sign, and they can only carry what they can see. Four conditions follow from that, and four independent authorities reached the first of them last month without knowing it.
Every story, signed and delivered.
Subscribe to the kxco channel and get the headline, the AI-written key takeaways, and the chain-anchor link the moment we publish. Audio versions and per-ticker subscriptions arrive in the next iteration.